

原文发表于美国时间2021-12-6
一头成年非洲雄象的体重可达15000磅(约6.8039吨重)。如果您曾靠近过一头大象,我能给您的最好建议就是别挡它的路,因为如果它受到惊吓就会发狂并压垮您。
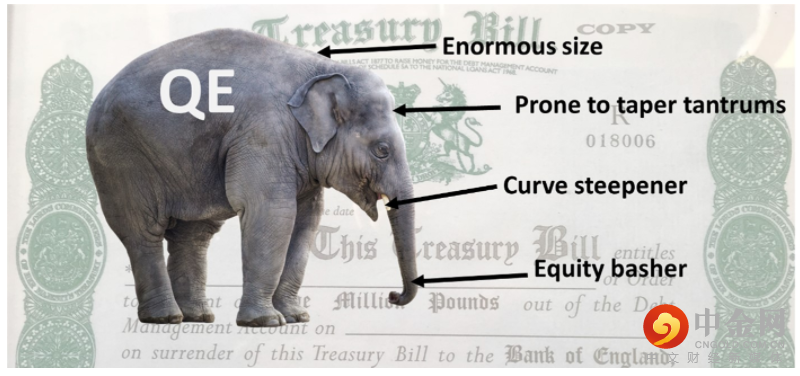
同样的情况适用于金融市场,2022年的市场主题将是通胀与利率政策之间的博弈,我们将不可避免地接近大象。
量化紧缩是一个少有人提及的主题,不过量化紧缩可能在接下来的货币政策周期发挥关键性的作用。
极少人完全了解市场上的大象,尤其是央行行长们,而且它们已经十分巨大了。例如,英国央行的资产购买工具APF目前持有8500亿英镑的资产,占全部债券总额的40%。不过迄今为止并未获得很多评论,仍然是金融市场“房间里的大象”。
量化宽松自2008年全球金融危机以来一直是市场背后的驱动性力量,央行行长们发现量化宽松是如此好用,十多年来一直是市场的关键支持力量和主导议题。
市场自量化宽松开始起就爱上了它,不过随着时间流逝变得不那么敏感了。
鲜有人了解当量化宽松逆转时会发生什么事情。
我们曾指出过为何出售资产购买工具APF持有的资产和加息之间的相互作用可能很关键。该结论更多聚焦于对收益率曲线和更广泛市场的可能影响。
我们目前所掌握的信息难以判断如上情况发生时的程度,如果我们够幸运的话,大象仅仅会拔掉一些树并吃掉它们,如果控制不当,则大象将开始碾压一切。
市场对“量化紧缩”的反应
没有人喜欢被碾压的感觉,所以市场倾向于在利率政策宣布之前做出反应并将政策变化纳入定价之中。
考虑到加息至1%的过程可能远比许多经济学家预期的要长,做市商在第一批债券被出售之前将可能有一定的时间进行仓位的调整。
投资者将考虑量化宽松对他们投资组合的影响,并在量化紧缩下做出相反的预期。所以,让我们回顾下量化宽松的初期发生了什么。
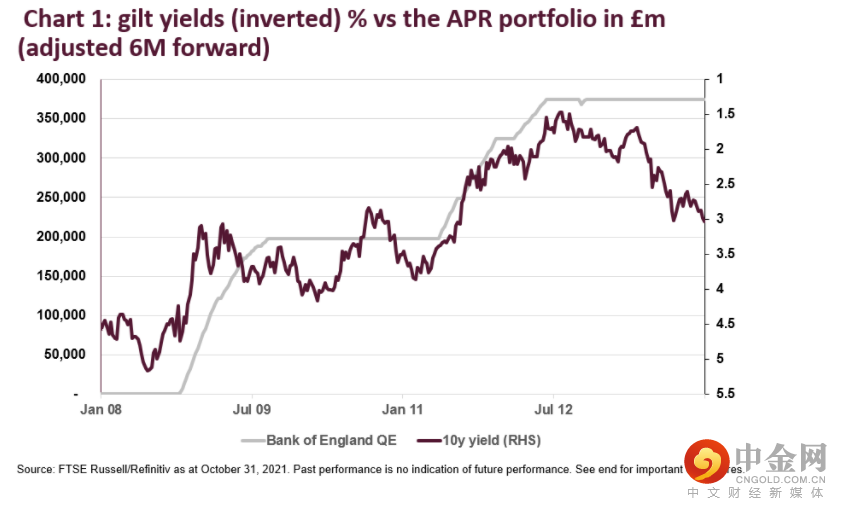
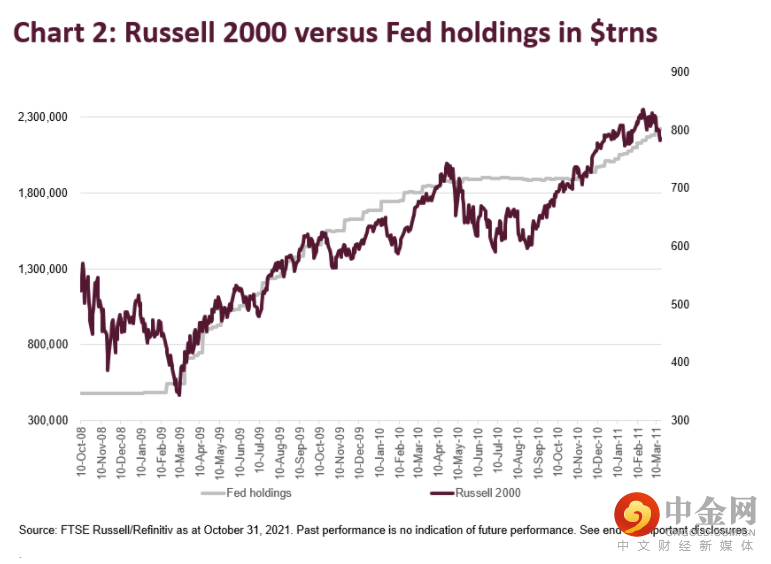
上面图表中的数据显示出央行资产购买项目与股票市场和债券市场反弹之间的密切关系。
实际上,图表清晰地证明了当央行资产购买停止时,投资者就会获利了结。
市场将面临的风险是,当量化宽松逆转时发生同样的情况,甚至因为投资者尝试在央行出售持有资产之前进行应对而提前发生市场下跌。
为何要触动市场上的大象?央行们希望通过重塑利率曲线而减缓通货膨胀。
此举的风险在于它可能过于有效而导致局面失控,或者在进行过程中产生意想不到的副作用。
请记住,量化宽松提高了包括房地产、古董、信贷、白银、股票和酒等很多类别资产的价值。
难以预估在量化紧缩期间会发生什么情况。
虽然央行的专家们还记得在2013年美国“紧缩恐慌”中的操作并留意其连锁影响,不过他们也必然预计到一旦设定了出售资产的时间表,将面临一个艰难的调整时期。
我们将在未来的文章中继续讨论量化紧缩的机制以及其对资产配置的意义。
This publication does not constitute an offer to buy or sell, or a solicitation of an offer to sell, any securities, or the solicitation of a proxy, by any person in any jurisdiction in which such an offer or solicitation is not authorised, or in which the person making such an offer or solicitation is not qualified to do so, or to any person to whom it is unlawful to make such an offer or solicitation. London Stock Exchange has taken reasonable efforts to ensure that the information contained in this publication is correct at the time of going to press, but shall not be liable for decisions made in reliance on it. Therefore, please note that this publication may be updated at any time. The information contained in this publication and any other publications referred herein are for guidance purposes only. London Stock Exchange and the coat of arms device are registered trade marks of London Stock Exchange plc.
Information posted on IBKR Traders‘ Insight that is provided by third-parties and not by Interactive Brokers does NOT constitute a recommendation by Interactive Brokers that you should contract for the services of that third party. Third-party participants who contribute to IBKR Traders’ Insight are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from London Stock Exchange and is being posted with permission from London Stock Exchange. The views expressed in this material are solely those of the author and/or London Stock Exchange and IBKR is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to sell or the solicitation of an offer to buy any security. To the extent that this material discusses general market activity, industry or sector trends or other broad based economic or political conditions, it should not be construed as research or investment advice. To the extent that it includes references to specific securities, commodities, currencies, or other instruments, those references do not constitute a recommendation to buy, sell or hold such security. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
这篇文章已被翻译成中文如英文版本和中文版本之间有任何不一致,以英文版本为准。该文章中的分析仅为提供信息,不是也不应该被视为推销或招揽购买任何证券。文章中讨论的一般市场活动、行业或领域趋势、或其它基于广泛的经济或政治条件的内容,不应被解释为研究结果或投资建议。讨论中提及包括的特定证券、商品、货币、或其它产品均不构成IB推荐购买,出售或持有此类投资的建议。本材料不是也不意图针对个别客户的特定财务条件、投资目标或要求。在根据本材料采取行动之前,您应该考虑是否适合您的具体情况,并在必要时寻求专业建议。






举报电话: 13816368049
